News analysis ·
Why global finance rules land unevenly: the FSB review
The FSB proposed eight modernisation principles and found home politics and law drive uneven G20 reform adoption. How soft law works.
The Financial Stability Board published two documents on 14 October 2026: a draft set of principles for modernising financial regulation, and a review of why G20 reforms have been adopted unevenly. Together they show a basic feature of global finance rules that headlines rarely explain. This article looks at how a body that cannot pass laws still shapes them, and where that chain breaks.
What the FSB released
The first document is a consultation. The Financial Stability Board proposes eight broad principles that member-jurisdiction authorities would apply. The stated goal is to keep regulation and supervision able to handle new technologies, new products, emerging vulnerabilities and shifting economic conditions, while nudging countries toward similar approaches. Comments are due by 8 January 2027, and the FSB plans a final version in the first half of 2027.
The second document is the 2026 report of the G20 Implementation Monitoring Review. It asks whether the way the FSB builds, words and presents its policies affects how well members put them into practice. It looks back at reforms agreed after the 2008 Global Financial Crisis. The work started in 2025, when South Africa, then holding the G20 Presidency, asked the FSB to examine how it promotes and tracks reforms. A working group chaired by Randal K. Quarles, a former FSB Chair and former Federal Reserve Vice Chair for Supervision, runs it. This is its second report.
How this works: rules without a lawmaker
The FSB is a coordinating body. According to the Financial Stability Board, it brings together authorities from 24 countries and jurisdictions, plus the global standard-setters, and reaches about 70 other jurisdictions through six Regional Consultative Groups. It is chaired by Andrew Bailey, who heads the Bank of England, and its Secretariat sits in Basel, hosted by the Bank for International Settlements.
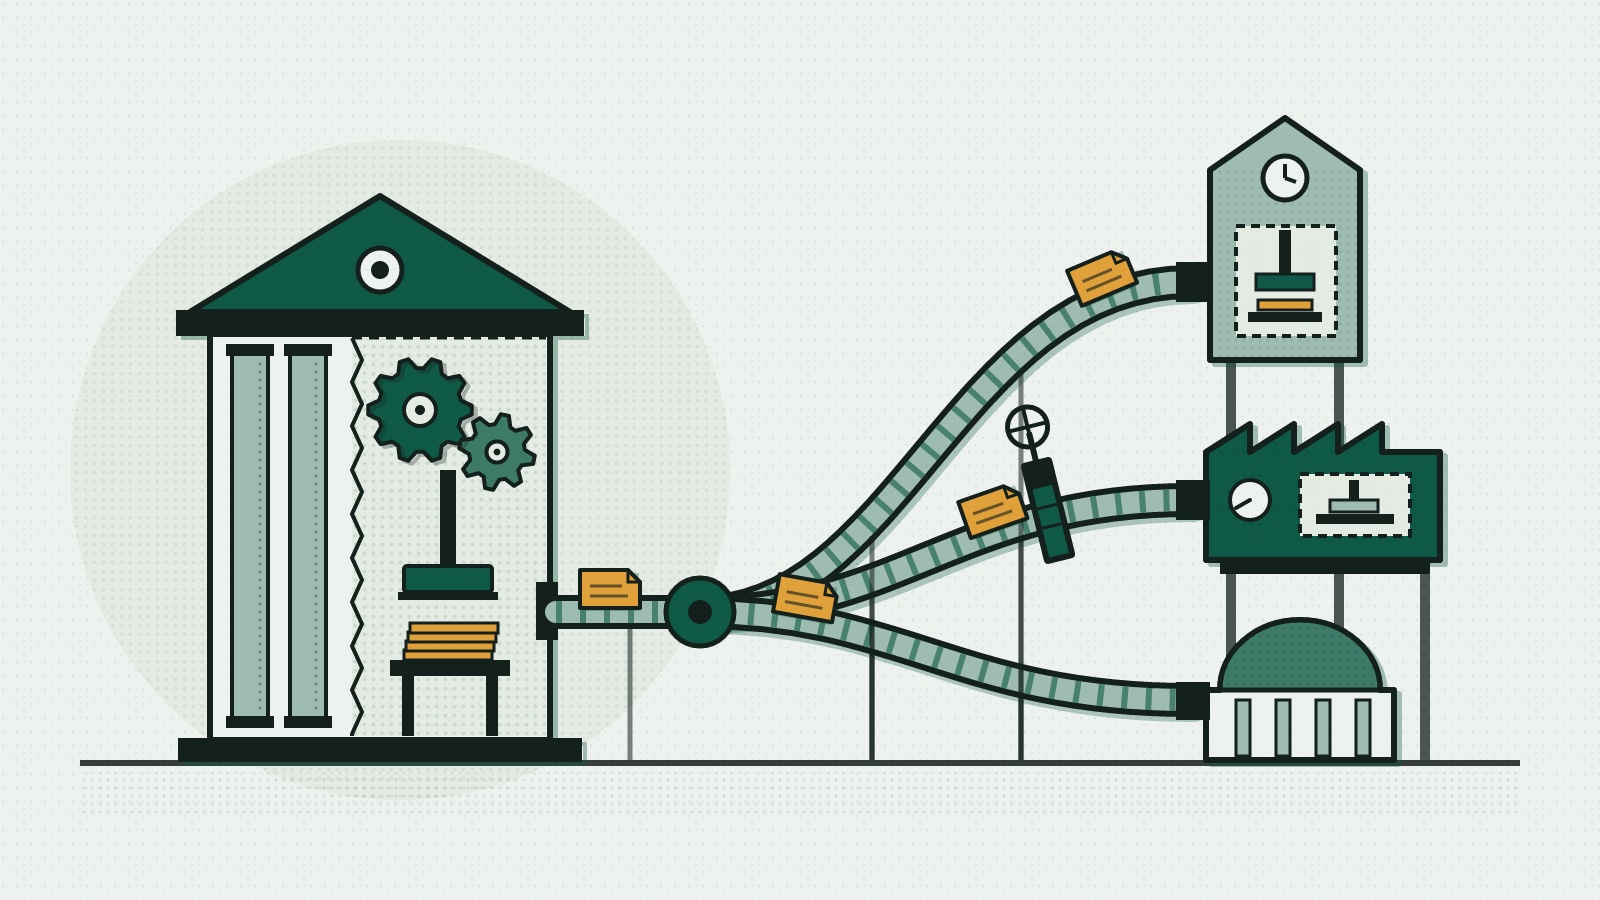
What the FSB cannot do is bind anyone. Its standards are often called soft law: political commitments, not statutes. A reform only reaches a bank, an exchange or a payment firm after several handoffs:
- Mandate: G20 leaders ask for work on a problem, such as a weakness exposed by a crisis.
- Agreement: the FSB and standard-setting bodies draft a standard, consult on it, and members sign up.
- Transposition: each country turns the standard into its own law or rules, through its parliament or regulators.
- Supervision: national supervisors apply those rules to the firms they oversee.
- Monitoring: the FSB tracks progress and reports back, which is the job of the review published this week.
Each handoff is a point where speed and detail can change. A standard agreed in one room becomes many national versions, written in different legal languages and passed on different timetables. That is the plumbing behind the phrase uneven implementation.
What the review found
The main finding points to home conditions. The report states that "national circumstances – including legal frameworks, market structure, and political capacity – are the main reason why implementation has been uneven". In plain terms: a country with a slow legislative process, a very different market, or little political room to act will fall behind, whatever the FSB writes.
The review also turns the lens inward. It says that in some cases the difficulty traces back to the FSB's own policy process, including too little attention to how hard a standard would be to apply. Its conclusion is that targeted, well calibrated changes to how the FSB develops policy are one part of the fix. This builds on findings from 2025 that implementation had slowed in a worrying way, which the FSB said could weaken the system's ability to absorb future shocks.
What changes, and for whom
Nothing changes for firms or consumers today. The principles are a draft, and even the final version will be guidance for authorities, not rules for companies. The direct audience is regulators and supervisors in member jurisdictions.
The indirect effect can matter more. If the FSB writes standards with implementation in mind, national rules may arrive more aligned and with fewer gaps. For anyone using financial services across borders, including crypto platforms and payment firms, gaps between national regimes are where the same activity faces different rules, and where risk can move to the place with the lightest oversight. The FSB's stated aim is to keep existing levels of resilience or raise them, not lower them.
Open questions
The documents leave several things unclear. They do not say which of the eight principles will prove hardest to apply, or how the FSB will measure whether its own process has improved. They also do not settle a basic tension: the principles must respect each country's legal framework, yet the purpose is closer alignment. How far a standard-setter can push without legal power is the question underneath the whole exercise. The consultation responses due in January 2027 and the final report later that year are the next places to look.
Sources
- Financial Stability Board, 14 Oct 2026
- Financial Stability Board, 14 Oct 2026
How this post was made: an AI model drafted it from the sources listed above, and software checks ran before it went live without a human edit. Every figure has to match a listed source and no sentence is copied. It explains how the mechanism works; it is not investment advice.