News analysis ·
How bank dollars can meet crypto margin calls at weekends
N3XT joins Clear Markets' Collateralizer as a dollar custodian. We explain how cash can back derivatives margin without leaving the bank.
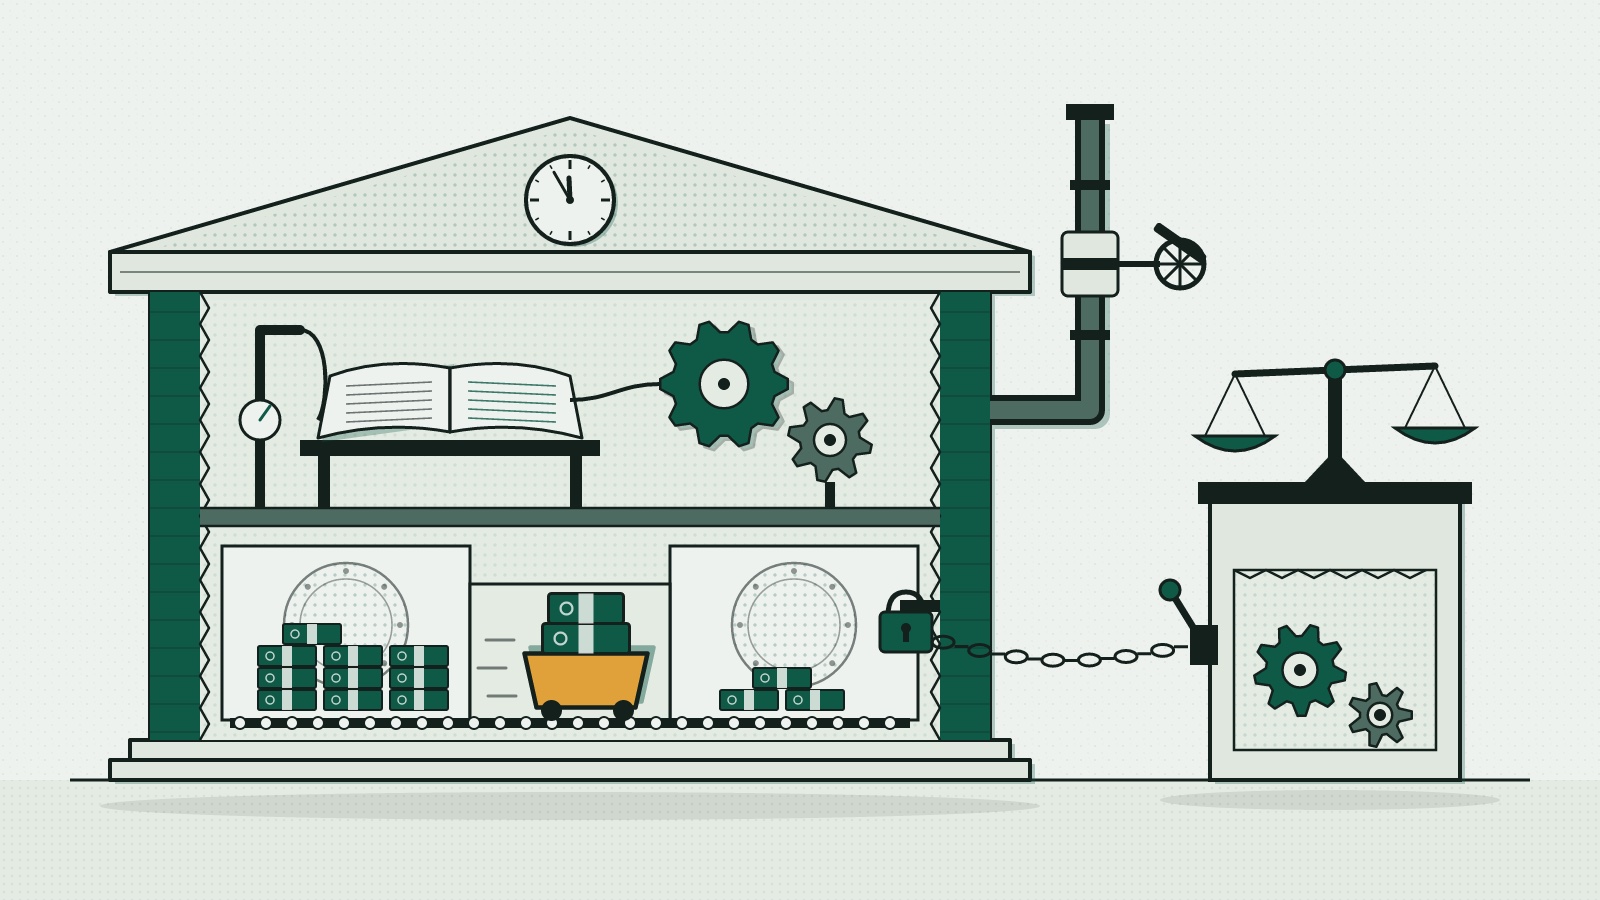
N3XT, a bank chartered in Wyoming, has joined the Collateralizer network run by Clear Markets as a custodian of US dollars, Unchained reported. The idea is that institutions can use cash held at the bank as margin for crypto derivatives that trade at every hour of the week. This article explains the plumbing: who holds the money, who only sees it, and why moving it inside one bank matters when the wider payment system is closed.
What was announced
According to an announcement Unchained received before its Thursday release, dollars deposited at N3XT can be pledged as collateral for swap, option and forward positions on the Clear Markets Swap Execution Facility, known as CMSEF. CMSEF is an institutional venue for crypto derivatives that is open around the clock, and the companies said it has held full CFTC registration since 2016. According to the firms, that cash may also be used to top up balances on other exchanges or to secure loans.
N3XT started operating in December 2025. Its founder is Scott Shay, who previously chaired Signature Bank, the lender that failed in March 2023. Jeffrey Wallis is CEO and president. Explaining the motive, Wallis said: "Capital markets are moving toward an increasingly 24/7 environment, and institutions need dollar infrastructure that can move instantly and with the markets".
How this works: margin, custody and control
A derivative is a contract whose value depends on something else, such as the price of bitcoin. Because either side might lose money, a venue asks traders to post margin. Initial margin is a deposit made when a position opens. Variation margin is the money that moves as prices change, so losses are covered before they grow. If prices move on a Sunday, the margin call arrives on a Sunday too.
The setup splits apart jobs that are often bundled together:
- Custody: N3XT keeps the dollars in its own accounts, under account-control agreements.
- Control: an account-control agreement is a legal contract that lets a third party direct or block movements from an account, so the pledged cash cannot simply be withdrawn by the trader.
- Technology: Clear Markets supplies the software that links custodians to trading, and the firms said it never holds client money.
- Network: Collateralizer runs on its own, apart from the CMSEF trading venue, and ties a group of independent custodian banks together for collateral handling, according to Clear Markets.
The key detail is where the money moves. The companies said N3XT can shift funds between accounts on its own books at any time, so margin demands can be met outside banking hours, including weekends, while the cash stays inside the bank. A transfer between two accounts at the same bank is just an update to that bank's ledger. It does not need an interbank payment system, and those systems keep limited hours. That is the gap this design tries to close.
What kind of bank this is
N3XT holds a Wyoming special purpose depository institution charter. Under this charter the bank may not make loans, and its liquid holdings must cover 100% of what customers have deposited. N3XT says its deposits are matched one for one by cash and short-term US Treasuries. In plain terms, it is closer to a vault with a ledger than to an ordinary bank that turns deposits into loans.
There is an important limit. N3XT's website says it is not FDIC insured. Deposit insurance is the government backstop that repays ordinary depositors up to a cap if an insured bank fails. Without it, protection rests on the reserve rule and on the bank's own assets and conduct. Readers who want the wider picture can compare how custody protections differ between firm types.
What changes, and for whom
For institutions trading crypto derivatives, the main change is timing. Margin can be posted in dollars at night or at weekends without first moving cash out of a bank. Clear Markets president Shawn Dorsch said the aim is to make derivatives trading easier while collateral sits with an independent bank custodian.
Separating custody from the venue also matters for risk. If collateral sits at a venue and the venue fails, clients may become creditors in a messy process. Holding it at a separate custodian, under a control agreement, is meant to keep the cash identifiable and apart from the venue's own balance sheet. Both firms intend to explore other ways to use N3XT's round-the-clock transfers. None of this removes market risk: derivatives can magnify losses, and anyone trading them can lose money, including more than the margin first posted.
Open questions
The announcement gave no launch date, no transaction volumes, no fees and no client names. The release is also inconsistent on timing: Wallis said clients can now use the cash as collateral, while another passage describes pledging as something still to come.
Other questions follow from the design. How does the arrangement handle a dispute or a default at a weekend, when courts and other banks are closed? How does a bank that cannot lend meet sudden large outflows if many clients move cash at once? And how will users weigh the absence of deposit insurance against the full reserve rule? The reports do not say.
Sources
- Unchained, 15 Oct 2026
How this post was made: an AI model drafted it from the sources listed above, and software checks ran before it went live without a human edit. Every figure has to match a listed source and no sentence is copied. It explains how the mechanism works; it is not investment advice.